How much does it really cost to sell a home in the Triangle in 2026? More than most sellers expect, because the biggest expenses stop being obvious once you look past the commission line. Listing fees, buyer concessions, closing costs, prorated taxes, carrying costs, and the slow bleed of a listing that sits too long can quietly remove five figures from your equity. This post names the hidden costs of selling, explains why they hit harder in a cooling market, and shows you how to keep more of them in your pocket.
Plenty of sellers fixate on one number at closing and feel the rest later. The good news is that every one of these costs is knowable in advance, and several are controllable. The strongest control of all: with the Zero Listing Commission program, the listing-side commission drops to $0 when you buy your next home through our team within 90 days. Here is the full picture of what is quietly working against your equity, starting with the line item most sellers never question.
The commission you can actually control
On a $500,000 home, a traditional listing commission around 3% works out to $15,000 straight out of your equity. That is not a tax, not a closing fee, and not an expense you are required to pay by law. Commissions are fully negotiable, and the amount is set by the agreement you sign, which means it is also the line item with the most room to change.
Traditional Listing
-$15,000+
Typical listing-side commission paid out of your equity on a $500,000 sale.
Zero Listing Commission
$0
Listing-side commission when you buy your next home through our team within 90 days.
That single decision is worth more than every other cost on this list combined, and it is entirely within your control. Now the costs that are easier to overlook.
Four costs that rarely show up in sellers' math
Ask most sellers what their sale cost them and they quote one number: the commission. The truth is messier, and in 2026 it is more relevant than ever. Here are the four costs that hide in plain sight.
1. Buyer concessions and inspection credits
When buyers have options, sellers pay to close the gap. Rate buydowns to make the purchase affordable, closing-cost credits, and repair concessions after the inspection are all coming out of your net, line by line. None of these are new, but in a buyer-friendly market they become the rule rather than the exception, and together they can rival the commission you thought was the whole story.
2. Closing costs, title work, and prorated taxes
Escrow, title insurance, attorney or closing fees, recording charges, and prorated property taxes all land on your settlement statement. If your home is in an HOA, expect prorated dues as well. These add up to real money that most sellers never budget for until the closing disclosure arrives.
3. Carrying costs on a home that keeps costing you
The mortgage, insurance, utilities, and upkeep do not pause while your home is listed. And if you buy your next home before you sell the current one, you are carrying two households at once, two mortgages on top of two sets of utility bills. A coordinated sell-and-buy closes that gap instead of stretching it.
4. The overpricing tax
A home priced above what the data supports does not sell for more, it sells later. Buyers see the days on market, they assume something is wrong, and their offers get more aggressive with every passing week. By the time the price is cut to the level it should have started at, the listing has lost its momentum and the seller has lost negotiating leverage. An honest, data-driven pricing strategy is worth more than any single repair you could spend on.
Add it up and a "standard" home sale can shed $20,000 to $30,000 in equity between the commission, concessions, closing costs, and carrying costs, before you spend a dollar on your next move. In a market where the median Triangle home is worth roughly $450,000, that is a meaningful slice of everything you built.
Why hidden costs hit harder in a cooling market
The Triangle is not the seller's market of a few years ago. As of September 2026, market watchers describe the Raleigh metro as having shifted into a rare buyer's market: inventory has climbed while demand cooled, the median sale price has drifted to roughly $450,000, a bit below where it sat a year earlier, and homes are taking a median of about 39 days to sell while 30-year fixed mortgage rates sit at 7% and above.
Every one of those conditions feeds the hidden costs above. Longer days on market raise carrying costs. Buyer leverage means more concessions and repair credits. A price that missed the market by even a few percent forces a reduction that buyers read as a signal. When your equity is doing the heavy lifting, every leak matters more.
The good news: the biggest cost is the easiest one to remove. You cannot control mortgage rates, and you cannot control how many buyers show up, but you can control what you pay to sell, and that is the lever zero commission pulls for you.
How Zero Listing Commission removes the biggest cost and shrinks the rest
The model is simple: list with us, buy your next home through our team within 90 days, and the listing-side commission is $0. But that is only half the story, because the program is built to keep the whole cost stack small:
- Zero listing commission protects five figures of equity the moment you sign, before buyers submit a single offer.
- Premium marketing that shortens days on market: professional HD photography, cinematic 4K video, licensed drone footage, Zillow Showcase placement, a custom property website, glossy catalogs, neighborhood door-hanger campaigns, and targeted digital ads on Facebook, Instagram, and Google.
- Data-driven pricing from day one so your home launches where the market actually is, which is the cheapest cure for the overpricing tax.
- One team for both sides of your move, with the 90-day window counting from your sale closing, so you are not stuck carrying two homes while you wait for the other half of the puzzle.
- Full-service representation and negotiation by an experienced broker at every step, from screening buyers to the final signature.
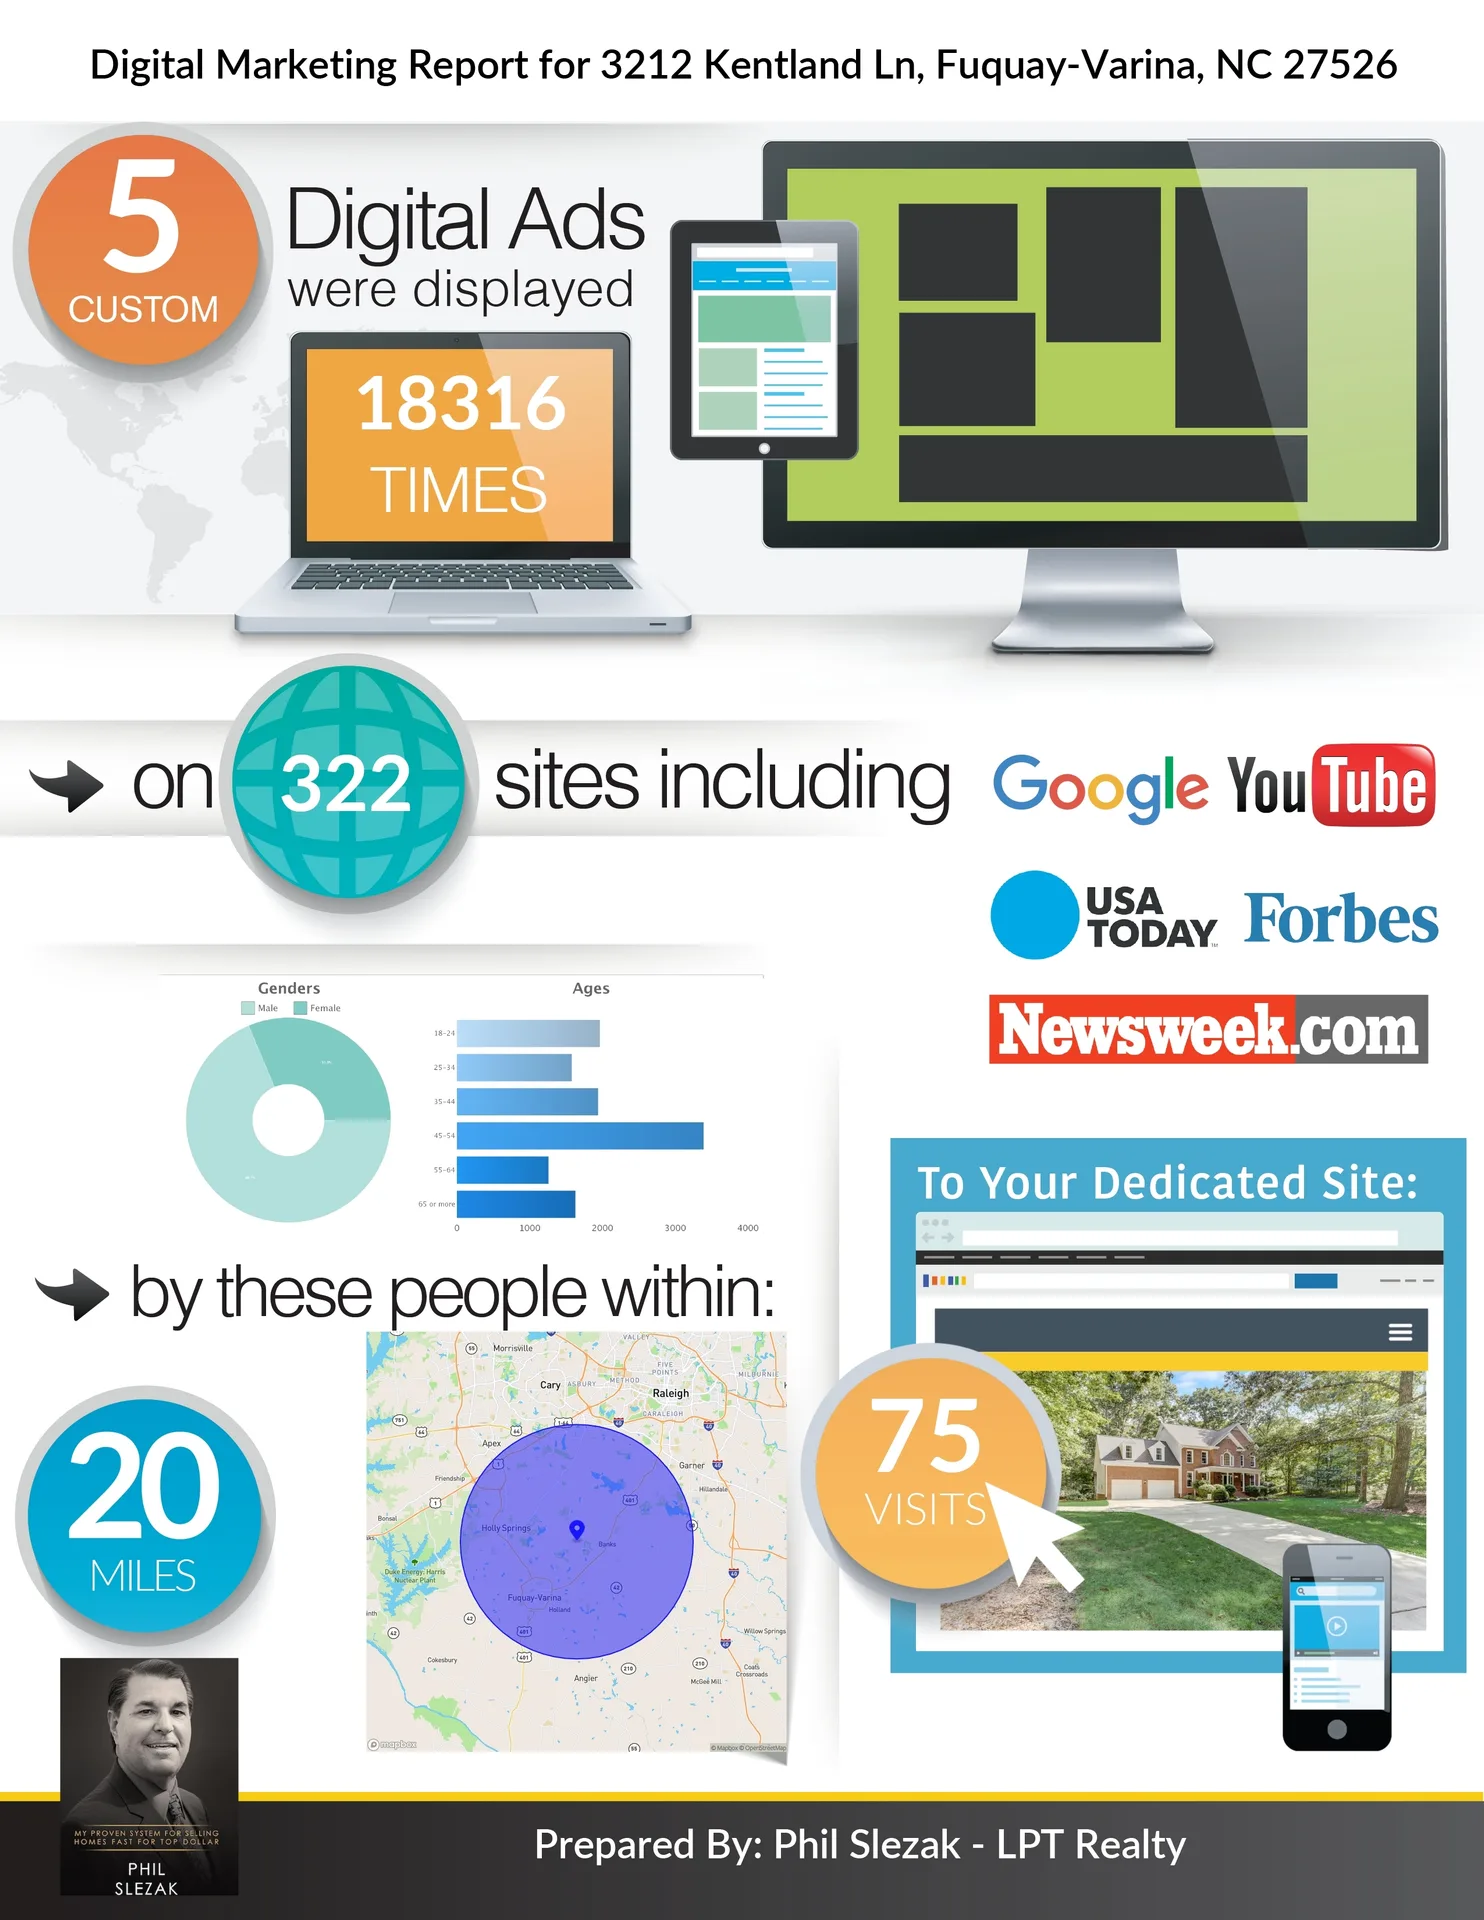
Faster sales, fewer concessions, no listing commission, and no double-carrying gap: each one is a line item that stops eating at your equity. See the full marketing program or step through how the program works.
The questions sellers ask us about costs
What are the hidden costs of selling a home in the Triangle?
Beyond the listing commission, sellers routinely pay buyer concessions and inspection credits, closing costs and title work, prorated taxes, carrying costs while the home is listed or while they hold two homes at once, and the price reductions that come from overpricing in a slower market. Together they can quietly remove five figures from your equity.
How much does a listing commission cost on a $500,000 home?
A typical listing-side commission around 3% on a $500,000 home is $15,000 straight out of the seller's equity. Commissions are fully negotiable and not set by law, so the exact number varies by home and market, but for most Triangle sellers it runs comfortably into five figures.
How does a cooling market add to seller costs?
In a buyer-friendly market, sellers are more likely to pay rate buydowns, closing-cost credits, and repair concessions to close the deal. Homes also sit longer, which raises carrying costs and gives buyers more leverage in negotiation, and overpriced listings often end in price reductions that shrink the final net.
How does zero commission protect my equity when I sell?
With Zero Listing Commission, the listing-side commission is $0 when you buy your next home through our team within 90 days. The premium marketing program, full-service representation, and data-driven pricing stay in place, so your home sells faster and closer to market value and less equity leaks out through the costs above. Check the FAQ page for more.
The bottom line
Selling a home in the Triangle in 2026 will cost you more than the commission, and in a cooling market every one of those costs is amplified. The strongest defense is simple: remove the biggest line item you control, and market your home well enough that the rest never get a chance to grow.
Zero listing commission, premium marketing, one team for both sides of the move, an honest price from day one. That is how you keep your equity instead of watching it get divided into fees.
Save Thousands. Keep Your Equity.
Raise your hand for a free equity check
Want to see the hidden costs on your specific home, and what $0 listing commission would put back in your pocket? Head to zerolistingcommission.com and raise your hand for a free, no-obligation Equity Consultation with Phil and his team. We will run the numbers on your place and show you exactly what you keep.
- The $15,000 Question: What Zero Listing Commission Really Puts Back in Your Pocket
On a $500K sale, a typical 3% listing commission is $15,000 straight out of your equity. Here is what keeping that money means for Triangle sellers.
- Why 'Zero Commission' Is Not a Discount Brokerage
A discount brokerage cuts the service to cut the fee. Zero Listing Commission waives the listing commission and keeps the premium marketing stack.
- Should You Wait for Mortgage Rates to Drop?
The real cost of waiting for Triangle sellers, and why the fee you can control matters more than the rate you cannot.
Real estate commissions are fully negotiable and not set by law. Zero Listing Commission listing fee waivers apply when you list and purchase your replacement home through Phil Slezak Real Estate. Market figures cited from recent Triangle real estate data, and savings figures are illustrative examples, not a guarantee for any specific property.